By Zachary Zanghi, Senior Partner
When I work with clients, I always encourage them to think beyond today’s market movements or this year’s tax return. True financial planning is about preparing for the things you can’t see coming, and long-term care (LTC) is one of those areas that’s easy to put off until it becomes urgent.
But the truth is: the earlier you plan, the more flexibility, control, and peace of mind you’ll retain, for both you and your family.
What Is Long-Term Care?
Long-term care refers to personal or medical assistance people often need as they age or face chronic illness or disability. While many assume it means a nursing home, most long-term care is provided at home or in settings like assisted living or adult day care centers.
There are three key types of care to understand:
- Skilled care – 24/7 medical attention from licensed providers
- Intermediate care – Occasional professional oversight for health conditions
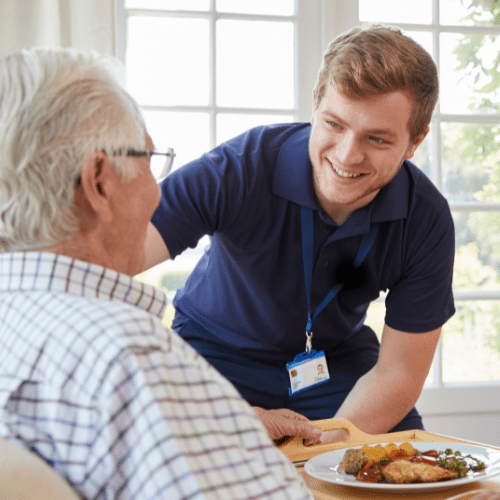
- Custodial care – Help with everyday tasks like bathing, eating, or dressing.
(This is the most common form, and the least likely to be covered by insurance.)
Generally, you are eligible for LTC plan benefits if you lose the ability to independently perform at least two Activities of Daily Living (ADL) for at least 90 days – or require substantial supervision due to a severe cognitive impairment.
The six ADLs are:
- Eating
- Bathing
- Dressing
- Toileting
- Transferring
- Continence
Why Planning Ahead Matters
Many people underestimate their chances of needing long-term care. According to the U.S. Department of Health and Human Services:
- Over half (52%) of those age 65+ will need some type of LTC
- Even younger adults (ages 40–50) face an 8% chance of needing it due to disability
Medicare vs. Medicaid: Don’t Be Misled
Many assume Medicare will handle long-term care. It won’t, at least, not the way most people need. Medicare only offers limited, short-term skilled care, not the custodial support most families rely on.
Medicaid, on the other hand, does cover long-term care, but only after you’ve spent down most of your assets. That’s a path few families willingly choose.
Pay-As-You-Go vs. Long-Term Care Insurance
While some clients prefer to self-fund long-term care (especially if they want flexibility), it’s rarely sustainable if care is needed over many years.
That’s where long-term care insurance can play a valuable role. A solid policy can:
- Preserve your estate
- Expand your care choices
- Reduce stress on loved ones during difficult times
When evaluating a policy, consider:
- Daily benefit amount
- Length of coverage (benefit period)
- Waiting period before benefits begin (elimination period)
- Inflation protection
- Eligible care settings
Also, for U.S. taxpayers, LTC insurance premiums may be partially tax-deductible depending on your age:
| Age Range | 2024 Deductible Limit |
| 40 or under | $470 |
| 41–50 | $880 |
| 51–60 | $1,760 |
| 61–70 | $4,710 |
| 70+ | $5,880 |
| (Source: IRS, 2024) |
Why This Matters to Me Personally
This topic hits close to home.
My father had a successful career, but like many, lacked a comprehensive financial plan. During the 2008–2009 financial crisis, I saw firsthand how quickly things could unravel, and it’s one of the reasons I entered this profession.
More recently, he was diagnosed with Alzheimer’s disease. That diagnosis has brought the issue of long-term care planning into sharp focus. I worry about whether he’ll have access to the best possible support, care that could significantly improve his comfort and quality of life.
This is not just theory. For many families, it becomes deeply personal.
How We Can Help
At Rosefinch Risk Management we help clients fit long-term care protection into their overall financial plan. Whether it’s comparing insurance options, weighing cover against self-funding, or considering international tax and residency issues, we aim to bring clarity to what can be an emotionally loaded topic.
If you already work with a Rosefinch advisor, your cover can be matched to the plan you have built together, so you’re not caught off guard if you suddenly need to pivot.
Final Thoughts
Thinking about long-term care isn’t easy. But facing it now puts you in control, of your care, your finances, and your legacy.
If you’d like to explore how long-term care fits into your overall plan, we’d be happy to talk.
Let’s have that conversation before it becomes urgent.
Disclaimer: Some of the content of this communication was provided by third parties of Rosefinch. We have not verified the information contained herein, but we believe the content is reliable.
Sources:
- U.S. Department of Health and Human Services, LongTermCare.gov (May 2022)
- Genworth Financial, Cost of Care Survey 2022
- IRS Publication 502 (Medical and Dental Expenses), 2024
- LTCG 2023 Lincoln Financial Cost of Care Survey
Speak to our team
Rosefinch Risk Management can help you work out what cover fits your plan. Already working with a Rosefinch advisor? They can arrange this for you.